

By BLAISE UDUNZE I Thureday, Sept 17,2026
LAGOS, Nigeria – Nigeria has become very good at celebrating economic milestones that ordinary Nigerians can barely afford to participate in. Now comes perhaps the most spectacular example yet.
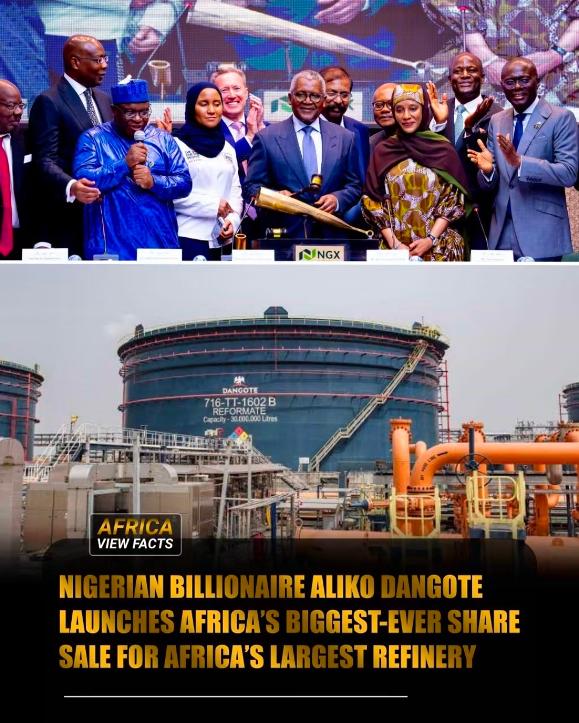
Africa’s biggest refinery has opened its doors to public ownership in what is being billed as the continent’s largest-ever initial public offering. Currently, there is strong demand and intense interest as the Dangote Petroleum Refinery is offering 4.1 billion shares at N525 each, seeking to raise about N2.15 trillion, or roughly $1.6 billion. The refinery is being valued at about N63 trillion, equivalent to approximately $47.6 billion.
The sales pitch is seductive, being classified as the “people’s IPO”, an opportunity for ordinary Nigerians to own a piece of one of Africa’s most ambitious industrial projects.
But there is a brutally inconvenient question hanging over the celebration, which brings to bear one question, such as, What happens when the people being invited to buy shares in the refinery are the same people struggling to buy the petrol it produces? That is Nigeria’s latest economic contradiction.
On one side stands a $47.6 billion industrial giant, operating at full capacity and producing up to 700,000 barrels per day, with plans to double capacity to 1.4 million barrels per day. On the other stands the Nigerian consumer, confronting another increase in petrol prices, rising transport costs, stubborn food inflation and shrinking purchasing power.
The refinery is getting bigger. The IPO is getting bigger. The valuation is getting bigger. But for millions of Nigerians, the question remains painfully small: Can I still afford to get to work tomorrow? That is the uncomfortable story behind Dangote’s “people’s IPO”.
Only days before the public offering opened, Dangote Refinery increased its petrol gantry price from N1,265 to N1,350 per litre, an N85 or roughly 6.7 percent increase. Retail prices subsequently moved above N1,400 in several locations, with reports of about N1,430 in parts of Abuja and even N1,450 in some markets.
The timing could hardly be more politically and economically striking. Nigeria is being told: buy shares in the refinery. The Nigerian consumer is responding: with what money?
This is not an argument that Dangote Refinery should sell petrol below cost. Nor is it an argument that a private company should be transformed into a social-welfare agency. It is a much bigger argument.
Nigeria spent decades suffering the absurdity of being an oil-producing country that imported much of the refined petroleum it consumed. Nigerians were filled with ecstasy and had high expectations that the Dangote Refinery would represent a decisive break from that humiliating contradiction, and yes, one would say it has.
No doubt, indeed the refinery has become a major refining hub, helping Nigeria move towards refined-product self-sufficiency and exports. Its scale is extraordinary. Its financial performance is extraordinary. Reuters reports that the refinery generated more than $13 billion in revenue and $1.82 billion in net profit in the first half of the year.
But the concern today for many is why does the Nigerian consumer still feel so economically vulnerable to petrol-price increases? Because industrial success and consumer welfare are not the same thing. That distinction must not be lost in the euphoria surrounding the IPO.
The refinery can be highly profitable while petrol remains expensive. The refinery can create enormous shareholder value while transport fares rise. The refinery can become Africa’s largest public offering while households cut the quantity of food they buy. The refinery can become a $47.6 billion company while millions of Nigerians experience their own purchasing power becoming smaller.
That is the irony. And the numbers are unforgiving. Nigeria’s headline inflation rate, after the country’s statistical rebasing, has remained around the mid-teens in 2026. The latest NBS data show headline inflation at 15.39 percent, while food inflation stood at 19.57 percent.
For the economist, these are percentages. For the household, they are smaller portions. Less rice. Less meat. Less transport. Less electricity. Less savings. Less investment. Less everything.
That is why the argument that “inflation is falling” can sound almost insulting when prices remain dramatically higher than they were before the recent cost-of-living crisis. Disinflation does not mean Nigerians have suddenly recovered their lost purchasing power. It simply means prices may be rising more slowly.
The Nigerian workers who saw the cost of living explode after the 2023 petrol subsidy removal do not recover that lost purchasing power merely because the inflation rate later declines. The price level has changed. That is the problem. And petrol sits right in the middle of it.
Nigeria is an economy where roads carry an enormous share of commerce. Goods must move. Workers must move. Farmers must move produce. Traders must move inventory. Children must get to school. Employees must get to work.
When petrol becomes more expensive, transportation becomes more expensive. When transportation becomes more expensive, food becomes more expensive. When food becomes more expensive, households have less money for everything else. That is how N85 becomes much more than N85.
The latest petrol increase may look modest when viewed from the refinery’s balance sheet. But for a commercial bus driver filling his tank, a trader moving goods from one market to another or a low-income worker commuting daily, the cumulative effect is anything but modest.
Nigeria’s transport system effectively turns fuel-price movements into a tax on mobility. And mobility is economic participation. A worker who spends more getting to work has less disposable income. A business that spends more transporting goods has fewer resources for expansion. A farmer who spends more moving crops to market earns less. A manufacturer facing higher logistics costs passes some of those costs to consumers. The chain continues until petrol becomes embedded in the price of virtually everything.
This is why the petrol debate cannot be reduced to what happens at filling stations. Petrol is a price-setting commodity in Nigeria. It influences the cost of moving the economy. And that is precisely why the Dangote story deserves tougher scrutiny.
For years, Nigerians were told that domestic refining would help solve the country’s petroleum problem. Now Nigeria has the refinery. But the consumer is still waiting for the relief.
Of course, there are legitimate reasons. Dangote buys crude in a global market. International crude prices matter. Exchange rates matter. Logistics matter. Financing matters. Refining economics matter. Competition matters. Taxes and regulatory costs matter.
Recent oil-market volatility has made the environment even more difficult and tougher for the people, with crude prices moving sharply higher amid geopolitical tensions. Reports this week put petrol prices in some Nigerian markets around N1,400-N1,450 per litre, with a tendency to rise without respite.
But that explanation should not end the conversation. It should begin it. Because if domestic refining does not meaningfully reduce Nigeria’s vulnerability to global oil-price shocks, then what exactly has changed structurally?
The answer cannot simply be that Nigeria now has a giant refinery. A refinery is infrastructure. Economic transformation is what happens after the infrastructure begins working through the economy.
That means cheaper and more reliable energy. More competitive businesses. Lower logistics costs. More employment. Higher real incomes. Greater purchasing power. And ultimately, a better standard of living.
Otherwise, Nigeria risks creating the most impressive industrial monument to a very old problem: an economy that produces wealth at the top while ordinary households continue to struggle at the bottom.
The IPO makes this contradiction almost impossible to ignore. At N525 per share, the minimum 10-share subscription costs N5,250, making the offer accessible to retail investors. But N5,250 is also real money to a Nigerian household.
It can buy food. It can pay transport. It can buy fuel. It can help settle a school-related expense. It can keep a small trader’s business moving for another day.
So the question is not whether Nigerians should buy Dangote shares. They may. The question is whether Nigerians have enough disposable income left after surviving Nigeria’s cost-of-living crisis to become meaningful investors.
That is the deeper indictment. Nigeria wants citizens to become investors before it has sufficiently restored their capacity to save. A country cannot build a mass investment culture on mass economic insecurity.
You cannot continuously squeeze household purchasing power and then wonder why retail participation in capital markets remains shallow. You cannot make survival more expensive and simultaneously expect millions of people to behave like long-term investors.
The “people’s IPO” therefore raises a much larger question about what inclusive capitalism should mean in Nigeria. Is inclusion simply giving people access to buy shares? Or is inclusion creating an economy in which people have enough income to buy those shares without sacrificing food, transport or healthcare? There is a difference. And it matters.
Dangote retains a dominant stake in the refinery, while the public offering opens a minority portion to investors. AP News and France24 News report that Dangote is expected to retain about 87 percent ownership.
So this is not the people taking control of the refinery. It is the people being invited to participate financially in its future. That is potentially significant. But participation is not empowerment if the underlying economy remains hostile to the participant.
Nigeria must therefore resist the temptation to declare victory simply because the IPO succeeds. A fully subscribed IPO would demonstrate investor appetite. A rising share price would demonstrate market confidence. A larger refinery would demonstrate industrial expansion. But none of these automatically demonstrates improved welfare.
The ultimate test is much harder. Can the average Nigerian live better? Can the bus driver buy fuel without immediately raising fares? Can the farmer transport produce without losing his margin? Can the trader restock without passing every increase to consumers? Can the salary earner commute without surrendering a disproportionate share of monthly income? Can a family buy food without discovering that the money that once lasted a week now lasts three days? Can Nigerians save after paying for survival?
Those are the metrics that matter. The danger is that Nigeria could become a country where corporate valuations rise faster than household incomes. Where the refinery becomes richer while the consumer becomes poorer. Where GDP grows but purchasing power contracts. Where foreign-exchange reserves rise but the cost of living remains crushing. Where tax revenues increase but citizens see little corresponding improvement in everyday life.
And where Africa’s biggest IPO becomes another spectacular financial event that ordinary Nigerians watch from the sidelines because they are too busy paying for transportation and food.
This is not an argument against Dangote. Indeed, Nigeria needs more Dangotes. It needs more large-scale industrial investment, more domestic manufacturing, more refining capacity, more private capital and more companies capable of competing globally.
What Nigeria does not need is the illusion that corporate success automatically equals national prosperity.
The Dangote Refinery should succeed. Its shareholders should prosper. Its expansion should create jobs. Its exports should earn foreign exchange. Its tax contributions should strengthen public finances. But the Nigerian consumer should not be forgotten in the celebration.
Because ultimately, the refinery was not built merely to create a magnificent corporate balance sheet. It was built in an economy where millions of people needed something more fundamental: energy security and economic relief.
And that brings us back to the central irony. Nigeria is asking its citizens to invest in a refinery worth roughly N63 trillion while those same citizens are watching petrol approach N1,450 per litre in some markets.
The company is talking about expansion. The investor is thinking about returns. The government is talking about industrialisation. But the ordinary Nigerian is calculating how much money remains after transportation and food. That is the distance between Nigeria’s economic narrative and Nigeria’s economic reality.
The Dangote IPO may indeed become a landmark in African capitalism. But it must not become another landmark in the country’s long history of confusing impressive economic statistics with improved human welfare.
Nigeria does not merely need richer companies. It needs richer citizens. It does not merely need a bigger refinery. It needs a stronger purchasing power. It does not merely need shareholders. It needs households with enough disposable income to become shareholders in the first place. And it does not merely need petrol produced in Nigeria. It needs an economy in which Nigerians can afford the petrol.
Africa’s biggest refinery may be producing more fuel. Africa’s biggest IPO may be creating more shareholders. But until the Nigerian people can feel the difference in their pockets, the most important economic product still missing from the refinery is prosperity.
Blaise, a journalist and PR professional, writes from Lagos and can be reached via: [email protected]
