

By BLAISE UDUNZE I Tuesday, Oct. 13, 2026
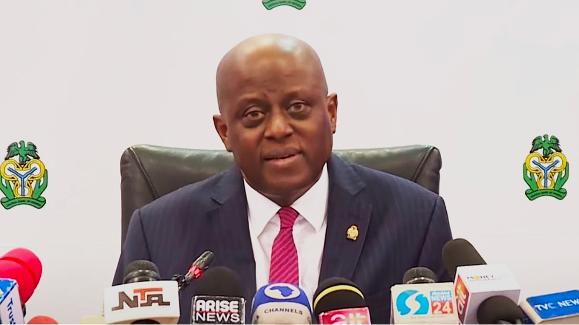
LAGOS, Nigeria – The Central Bank of Nigeria (CBN) held its 307th Monetary Policy Committee (MPC) meeting on September 21 and 22, 2026, opting to reduce the Monetary Policy Rate (MPR) from 26.5 percent to 23 percent.
While a 45 percent requirement does not mean lending automatically falls by 45 percent—given variations in funding structures, capital adequacy constraints, and liquidity buffers—it undeniably imposes a substantial drag on financial intermediation. Consequently, the CBN is sending dual, conflicting signals: the lower MPR signals policy easing, while the unchanged CRR reflects continued anxiety over liquidity management and financial stability
While this 350-basis-point reduction represents a significant adjustment to the policy-rate signal, it revives a critical question about monetary policy transmission in an economy starved of affordable credit: Can Nigeria effectively lower the price of money while maintaining a regulatory constraint that severely restricts the loanable funds banks can deploy?
This dilemma is particularly acute at a time when inflation has moderated, foreign reserves have strengthened, and the banking sector has completed a major recapitalisation exercise. If these indicators point toward a improving macroeconomic environment and a stronger financial system, why should deposit money banks continue operating under such a demanding reserve requirement?
In essence, Nigeria may have taken steps to reduce borrowing costs without doing enough to ensure that businesses and households can actually access loans.
Policy Signals vs. Regulatory Constraints
At its September meeting, the MPC retained the Cash Reserve Requirement (CRR) for Deposit Money Banks at 45 percent, set the CRR for merchant banks at 16 percent, and maintained a 75 percent CRR on non-Treasury Single Account (non-TSA) public-sector deposits. Simultaneously, the CBN adjusted the Standing Facilities Corridor to +50/-300 basis points around the MPR.
The apex bank framed these adjustments as an operational realignment designed to strengthen transmission and restore the MPR’s primacy as the benchmark rate. Importantly, this move was not a blanket declaration of an expansionary stance; rather, it was an attempt to ensure that policy decisions effectively filter down to market interest rates and real economic activity.
However, the key concern remains whether this adjustment translates into cheaper, more accessible credit. Warning signs are already evident.
In a report titled “MPR Cut: Why Cheaper Loans May Not Come Soon,” Premium Times highlighted factors that could delay rate-reduction transmission to borrowers. The report noted that the 45 percent CRR remains a primary bottleneck on lending capacity, while existing loan agreements and fixed repricing schedules naturally lag behind policy adjustments.
This dynamic introduces an inherent asymmetry into the financial system: deposit costs for banks may decline faster than interest rates charged on existing loans, widening net interest margins and boosting bank profitability long before real-economy borrowers experience meaningful relief.
While this is not necessarily evidence of misconduct—given that lenders must account for maturity schedules, credit risk, operating costs, and loan default probabilities—it raises a legitimate policy question: If recalibrating the MPR is intended to improve monetary transmission, how quickly should those benefits reach borrowers, and what structural barriers are preventing that from happening?
The Burden of the 45 Percent CRR
The CRR sits at the heart of this debate because it directly dictates the proportion of deposit liabilities banks must lock away with the CBN instead of deploying into loans or income-generating assets.
While a 45 percent requirement does not mean lending automatically falls by 45 percent—given variations in funding structures, capital adequacy constraints, and liquidity buffers—it undeniably imposes a substantial drag on financial intermediation. Consequently, the CBN is sending dual, conflicting signals: the lower MPR signals policy easing, while the unchanged CRR reflects continued anxiety over liquidity management and financial stability.
While both objectives are valid, the critical issue is whether their combined effect aligns with the credit expansion Nigeria urgently needs.
In another report, Leadership questioned the retention of the 45 percent CRR against the backdrop of rising foreign reserves and easing inflation, citing economists who urged the CBN to ease liquidity restrictions as macroeconomic stability returns.
The report referenced an estimate by Chapel Hill Denham that the CRR costs the banking industry up to ₦2.5 trillion annually in foregone interest income. While this figure reflects lost earning opportunities rather than a guaranteed volume of new loans, it underscores the heavy opportunity cost of tying up idle capital when the productive sector desperately needs credit.
Nigeria’s expanding foreign reserves—which strengthen external confidence and cushion against exchange-rate volatility—and moderating inflation provide room to reconsider the degree of monetary tightness. While inflation risks have not vanished, the CBN should clearly outline the specific conditions required to justify a CRR review, the risk factors that necessitate the current level, and its roadmap for balancing liquidity control with credit growth.
Recapitalisation and Productive Credit Allocation
This issue extends beyond monetary policy to the core objectives of the recent banking recapitalisation exercise, which raised ₦4.65 trillion.
An assessment by DataPro Limited placed the average Capital Adequacy Ratio (CAR) across the industry at 25.5 percent, while noting ₦2.9 trillion in loan write-offs—a sharp reminder of persistent asset-quality challenges and credit risks.
These figures highlight a fundamental reality: a stronger capital base enhances a bank’s capacity to absorb losses and accommodate larger exposures, but it does not automatically guarantee increased lending to manufacturers, farmers, exporters, or small businesses.
Banks must still evaluate default risks, collateral sufficiency, legal enforceability, and borrower commercial viability. Where macro risks remain high, extra capital reinforces balance sheets without producing a proportionate expansion in private-sector loans.
Therefore, the post-recapitalisation test cannot simply be measured by funds raised or regulatory thresholds met. It must evaluate whether banks are actively expanding sustainable credit to productive sectors without compromising underwriting standards.
If banks hold robust capital positions yet remain constrained by an aggressive CRR, policymakers must examine whether the regulatory framework is aligned with national economic growth goals. Demanding more lending is not enough; the operating environment must make lending commercially viable.
For Small and Medium-sized Enterprises (SMEs), this challenge is acute. SMEs lacking substantial collateral, audited records, or established banking relationships face steep borrowing costs or outright rejection—even when their operations are viable. Conversely, large corporations negotiate better terms, even though some account for notable default figures. Thus, a lower MPR may improve terms for elite corporate borrowers without meaningfully shifting the landscape for the businesses that need financing most.
Looking Ahead: An Evidence-Driven Framework
Monetary policy alone cannot fix structural bottlenecks. Nigerian manufacturers may benefit from lower interest rates, but high energy tariffs, foreign-exchange volatility, expensive imported inputs, and logistical hurdles remain heavy cost drivers. A cheaper loan cannot offset unreliable power or persistent operational inefficiencies.
Accordingly, the CBN must approach credit expansion as part of a broader economic blueprint. Rather than an abrupt overnight drop in the reserve requirement, the CBN could adopt a phased, evidence-driven CRR adjustment tied to key macroeconomic milestones: inflation expectations, systemic liquidity levels, FX market stability, and verifiable private-sector credit growth.
The central bank could also introduce targeted CRR relief or lending incentives for strategic sectors, accompanied by strict monitoring safeguards to prevent funds from being diverted into currency speculation or government paper. Historically, liquidity injections run the risk of flowing into risk-free government securities rather than the real economy; hence, the focus must remain on productive allocation, not just raw liquidity.
To ensure transparency, the CBN should establish clear benchmarks for reviewing the 45 percent CRR and regularly publish data tracking effective lending rates, loan application-to-approval ratios, disbursements, and credit flows to agriculture, manufacturing, and SMEs. Additionally, tracking interbank rates and Treasury bill yields will reveal how effectively the new MPR corridor is transmitting through money markets.
If the policy signal eases but actual borrowing costs stay elevated, the CBN must diagnose the root cause—whether it stems from funding costs, CRR drag, elevated credit risk, or limited banking competition.
Ultimately, the success of the 23 percent MPR will not be determined by the announcement itself.
Success will be measured by whether Nigerian entrepreneurs, manufacturers, farmers, and small business owners can obtain affordable, accessible, and sustained credit. Until then, the central question remains: Does monetary policy foster the conditions for real-sector growth, or do liquidity restrictions continue to prevent capital from turning into productive economic activity?
NB: Blaise Udunze, a journalist and PR professional, writes from Lagos and can be reached via: [email protected]
